Key Takeaways
-
Medigap premiums are only one part of the comparison. You should also look at what Medicare Supplement coverage pays, what remains your responsibility, and how supplemental coverage fits with your postal retiree health benefits.
-
Your best comparison is based on total coverage needs, not premium alone. Review cost sharing, provider access, prescription coverage, travel needs, household coverage, and coordination with your existing benefits before making a decision.
Understanding Medigap Premiums And Medicare Supplement Coverage
As a postal employee approaching retirement or a postal retiree, you may have several layers of health coverage to understand. Medicare may become part of that picture, along with health benefits available to eligible postal retirees.
Medicare Supplement Insurance, commonly called Medigap, is designed to work with Original Medicare. It can help with certain costs that Original Medicare leaves to you. However, Medigap is separate coverage with its own premium and coverage rules.
That makes it important to avoid comparing Medigap premiums in isolation. A lower premium does not automatically mean lower overall health spending. Likewise, broader supplemental coverage may not always be necessary when you already have other retiree health benefits.
The goal is to understand how each form of coverage fits together. The following seven areas can help you make a more complete comparison.
1. Medigap Premiums Versus Your Total Health Coverage Costs
What Should You Include When Comparing Premiums?
The Medigap premium is the regular amount you pay to maintain the supplemental policy. However, your premium does not represent your complete health care budget.
You may also have costs connected with Medicare and your postal retiree coverage. Depending on your coverage arrangement, you could have deductibles, coinsurance, copayments, or expenses for services that are not covered.
When comparing your options, consider:
-
Regular premiums for each form of coverage you maintain
-
Deductibles that may apply
-
Copayments and coinsurance
-
Prescription drug expenses
-
Costs for services outside your coverage
-
Potential out-of-pocket medical spending
Think in terms of your total coverage structure. This gives you a clearer view than comparing one premium by itself.
2. Medicare Supplement Coverage Versus Original Medicare Cost Sharing
Which Medicare Costs Could Remain Your Responsibility?
Original Medicare covers many eligible hospital and medical services, but it does not necessarily pay your entire share of covered care.
Medicare Supplement coverage is intended to help with certain gaps in Original Medicare. Depending on the standardized Medigap coverage you select, it may help with eligible deductibles, copayments, or coinsurance.
The amount of financial protection can vary by the type of Medicare Supplement coverage. This creates a tradeoff between premiums and the amount of cost sharing you could face when receiving care.
Instead of asking only what a policy costs, ask what financial responsibility it transfers away from you.
3. Medigap Coverage Versus Postal Retiree Health Benefits
Could Your Existing Coverage Already Fill Some Medicare Gaps?
This is especially important for postal retirees. Your retirement health coverage may already coordinate with Medicare and help with some expenses that Medicare does not fully pay.
Before adding Medicare Supplement coverage, review how your existing benefits work with Medicare.
Look for possible overlap in areas such as:
-
Hospital cost sharing
-
Medical service cost sharing
-
Other out-of-pocket protections
-
Prescription benefits
-
Additional health benefits
Paying for overlapping coverage may not provide the value you expect. On the other hand, assuming that two forms of coverage are identical can also create gaps.
Review the official documents for your postal health coverage and compare them with what the Medicare Supplement coverage actually provides.
4. Provider Access And Medicare Supplement Coverage
How Much Flexibility Do You Want When Choosing Providers?
Provider access can be an important part of your retirement health care strategy.
Medigap works with Original Medicare. Your access to physicians and facilities therefore generally centers on providers that participate in Medicare rather than a separate Medigap provider network.
This may matter if you travel, divide your time between different locations, or simply want flexibility when seeking care.
When reviewing coverage, consider how you normally receive health care. Check whether your doctors accept Medicare and whether your broader coverage arrangement creates any additional provider requirements.
A premium comparison tells you what you pay. A provider-access comparison tells you how practical the coverage may be when you need care.
5. Prescription Drug Coverage Versus Medigap Benefits
Does Medicare Supplement Coverage Pay For Your Prescriptions?
Prescription benefits require separate attention because Medigap should not be treated as comprehensive prescription drug coverage.
For postal retirees, this is particularly important because prescription benefits may already be connected with your postal retiree health coverage and Medicare coordination.
Do not assume that purchasing supplemental medical coverage automatically changes or improves your prescription benefits.
Instead, examine medical and prescription coverage separately. Determine where your drug benefits come from, how that coverage coordinates with Medicare, and what could happen to those benefits if you make a coverage change.
This can help you avoid creating an unintended gap while trying to improve another part of your health coverage.
6. Household Coverage Versus Individual Medigap Premiums
Will Your Spouse Or Family Member Need Separate Coverage?
Retirement health planning often happens at the household level, but Medigap coverage is individual.
That distinction can affect your budget. You and your spouse may have different Medicare status, health coverage needs, or eligibility for other retiree benefits. You should therefore avoid assuming that one coverage decision automatically works for both people.
Review each eligible household member separately. Consider each person’s Medicare enrollment, supplemental needs, prescription coverage, provider preferences, and other available insurance.
Then combine those individual decisions into a household health budget.
This approach gives you a more accurate picture of potential retirement expenses and helps prevent you from overlooking coverage needs for a spouse or other eligible family member.
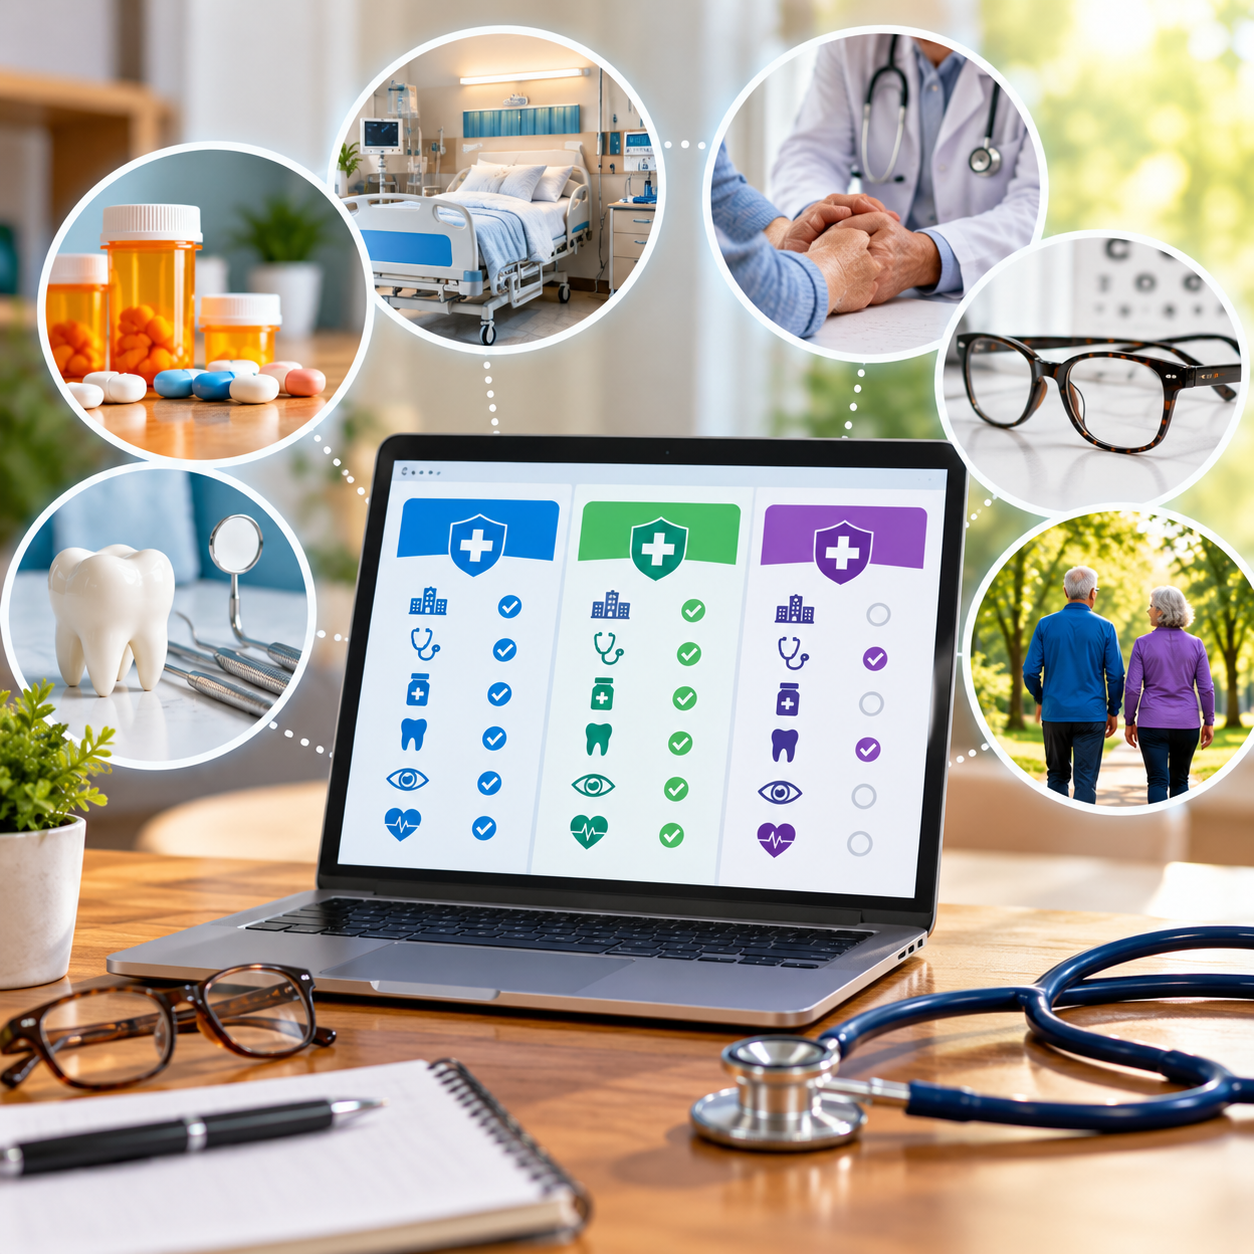
7. Coverage Beyond Routine Medicare Services
Which Health Expenses May Still Fall Outside Medigap?
Medicare Supplement coverage can reduce certain out-of-pocket costs associated with Original Medicare, but it does not turn Medicare into coverage for every health-related expense.
Some types of care may remain outside standard Medigap benefits. These can include services related to routine dental, vision, hearing, or long-term care needs, depending on the type of service and your other coverage.
Some Medicare Supplement coverage may also provide limited protection for qualifying emergency care during foreign travel. However, you should read the applicable coverage terms rather than assuming all international medical expenses are included.
Create a list of the health services you expect to use. Then identify which part of your coverage would pay for each category. This makes uncovered areas easier to see.
Building A Better Medigap Premium Comparison
What Should You Review Before Making A Coverage Decision?
A useful comparison should bring costs and benefits together. Start with your Medicare coverage and then add your postal retiree benefits. After that, consider what a Medigap policy would add.
Ask yourself whether supplemental coverage reduces meaningful financial exposure or mainly duplicates benefits you already have.
You should also examine how predictable you want your health spending to be. Some retirees may prefer paying more through regular premiums in exchange for reducing certain out-of-pocket costs. Others may place greater value on avoiding unnecessary overlapping coverage.
Your health needs can also change. A coverage arrangement that looks suitable based only on your current use of medical services may not reflect your longer-term priorities. Consider provider flexibility, travel, household needs, and the types of expenses that would be difficult for your retirement budget to absorb.
Making Your Medicare Supplement Coverage Work With Your Retirement Strategy
Medigap premiums matter, but they should be viewed as part of a larger retirement health coverage decision. As a postal retiree, you should consider how Original Medicare, Medicare Supplement coverage, prescription benefits, and your postal retiree health coverage interact.
Compare what you pay, what each layer covers, and where gaps or duplication could occur. Read your official benefit materials carefully before changing existing coverage. Your personal Medicare eligibility and postal retirement circumstances can affect how the different pieces work together.
For more guidance designed for postal employees and retirees, sign up on this website to receive updates and educational information that can help you evaluate your retirement health coverage choices.