Key Takeaways
-
A high-deductible plan can save you money on monthly premiums but requires you to pay more upfront before coverage kicks in.
-
A low-deductible plan reduces out-of-pocket costs for medical care but often comes with higher premiums.
Understanding Deductibles in Your PSHB Plan
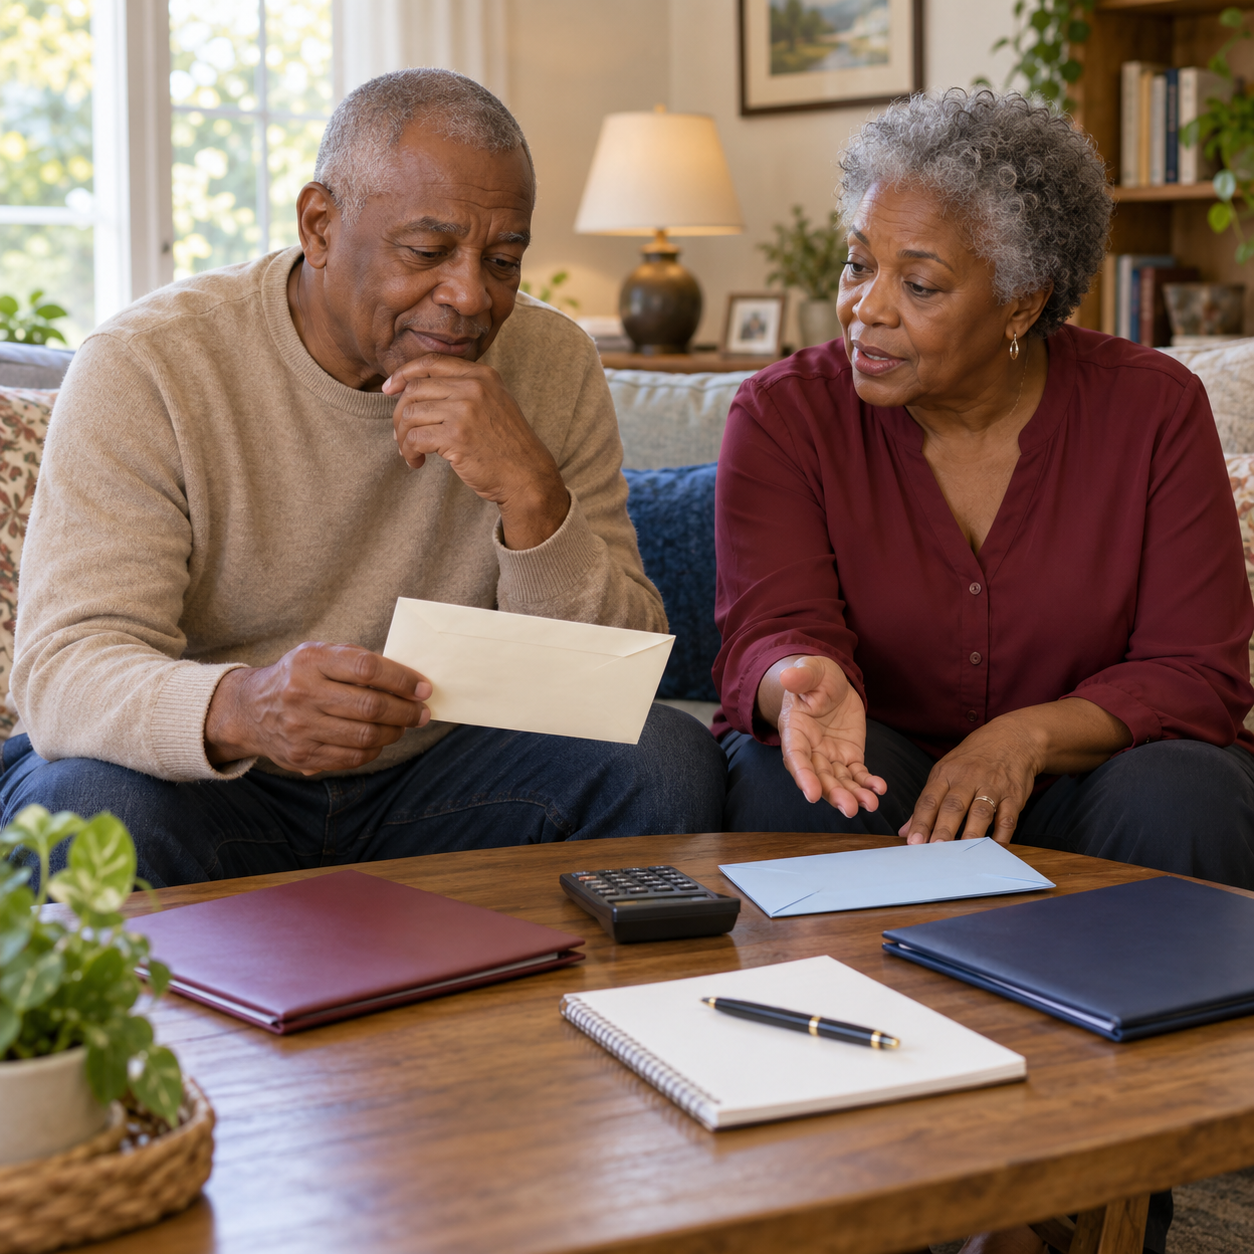
As a postal worker or retiree, choosing between a high or low deductible for your Postal Service Health Benefits (PSHB) plan can have a major impact on your healthcare costs in 2025. With deductibles steadily increasing, it’s important to weigh your options carefully. The right plan for you depends on your healthcare needs, budget, and risk tolerance. Let’s break down the pros and cons of each choice so you can make an informed decision.
What Is a Deductible, and Why Does It Matter?
A deductible is the amount you must pay out-of-pocket for covered medical expenses before your health plan starts sharing costs. Here’s what you need to know:
-
Applies to certain services – Deductibles typically apply to hospital visits, specialist care, and some medical procedures but may not include routine preventive care.
-
Resets annually – Your deductible starts over every January, meaning you need to meet it again each year.
-
Impacts your total healthcare spending – A higher deductible usually means lower monthly premiums but higher out-of-pocket costs when you receive care.
-
Affects cost-sharing calculations – Until your deductible is met, you may have to pay the full cost of medical services out-of-pocket.
Understanding how deductibles work helps you evaluate whether a high or low deductible is better suited for your needs in 2025.
High-Deductible Plans: Lower Premiums, Higher Risk
If you’re comfortable with paying more upfront for healthcare services but want to save on your monthly costs, a high-deductible plan might be the right fit.
Pros of a High-Deductible Plan
-
Lower monthly premiums – You pay less each month, which helps if you don’t frequently need medical care.
-
Potential for tax advantages – High-deductible plans are often compatible with Health Savings Accounts (HSAs), allowing you to save pre-tax money for medical expenses.
-
Good for healthy individuals – If you rarely visit the doctor or need expensive treatments, a high-deductible plan could save you money in the long run.
-
Encourages mindful spending – Since you pay more upfront, you may be more selective about seeking medical care, leading to cost savings.
Cons of a High-Deductible Plan
-
Higher out-of-pocket costs – Until you meet your deductible, you’re responsible for most medical expenses.
-
Not ideal for frequent medical needs – If you have a chronic condition or expect significant medical expenses, you may end up paying more out-of-pocket than with a lower deductible.
-
Unexpected costs – A sudden illness or injury can lead to large medical bills before your insurance coverage kicks in.
-
Limited coverage for some services – Certain specialized treatments may require higher upfront costs before coverage begins.
Low-Deductible Plans: Higher Premiums, Predictable Costs
For those who prefer predictable costs and lower upfront expenses for medical care, a low-deductible plan may be a better choice.
Pros of a Low-Deductible Plan
-
Lower out-of-pocket costs – You reach your deductible faster, meaning your plan starts covering costs sooner.
-
Better for ongoing medical needs – If you have regular doctor visits, prescriptions, or medical treatments, a lower deductible plan helps reduce expenses over time.
-
More predictable budgeting – You won’t face as many surprise expenses since your plan covers a greater share of your healthcare costs earlier in the year.
-
Less financial risk – You won’t have to worry about large medical bills accumulating before your coverage kicks in.
Cons of a Low-Deductible Plan
-
Higher monthly premiums – You pay more each month, even if you don’t need frequent medical care.
-
May not be cost-effective for healthy individuals – If you rarely visit the doctor, you might end up paying more in premiums than you would in medical expenses.
-
Can lead to overpaying – If you don’t use many healthcare services, you may be paying more in premiums without getting the full benefit of your plan.
Comparing Costs: What to Consider
To decide between a high or low deductible, ask yourself:
-
How often do I visit the doctor? If you have ongoing medical conditions, a low deductible may be worth the higher premiums.
-
Do I have savings for unexpected medical costs? If not, a low-deductible plan could provide more financial stability.
-
What’s my monthly budget? If lower premiums are a priority, a high-deductible plan may make more sense.
-
Am I planning any major medical procedures? If you expect surgery or specialist visits, a low deductible may be more beneficial.
-
Do I take prescription medications regularly? Medication costs can add up quickly, so a lower deductible might be better if you have ongoing prescriptions.
Additional Factors to Keep in Mind for 2025
-
Annual out-of-pocket maximums – Even if you choose a high-deductible plan, there is a limit to how much you’ll have to pay in a year.
-
PSHB plan changes – Each year, plan benefits and costs may shift, so reviewing updates during the Open Season from November to December is crucial.
-
Medicare integration – If you’re eligible for Medicare, coordinating coverage with PSHB can help minimize costs, particularly if you select a plan that offers enhanced benefits for Medicare enrollees.
-
Family coverage considerations – If you’re covering dependents, their healthcare usage should factor into your choice.
-
Preventive care benefits – Some high-deductible plans may still offer full coverage for preventive services, so checking the details is important.
Making Your Decision
Choosing the right PSHB plan for 2025 comes down to your personal healthcare needs and financial situation. If you rarely need medical care and want to save on premiums, a high-deductible plan could work for you. However, if you prefer predictable costs and lower out-of-pocket expenses when receiving care, a low-deductible plan might be the better choice.
Take the time to review your healthcare needs, budget, and expected medical expenses before enrolling. If you’re unsure which plan is right for you, consider speaking with a licensed agent listed on this website for expert guidance tailored to your situation.